Showing posts with label Paragon Health Institute. Show all posts

Wednesday, July 01, 2026

Fleshing out the ACA marketplace's alleged phantom enrollees, Part 2

Note: Free xpostfactoid subscription is available on Substack alone, though I will continue to cross-post on this site. If you're not subscribed, please visit xpostfactoid on Substack and sign up.

Your income next year may be $14,000? Can you earn a little more?


It’s time for Part 2 of our close look at Brian Blase’s claims in The Persistent Obamacare Enrollment Fraud and its top-line claim (heavily relied on by CMS) that in 2026, 6.2 million enrollments were “improper.” To reiterate a few big-picture points from Part 1:

1. Blase rhetorically conflates what he’s branded as “the great Obamacare fraud” with enrollments he deems “improper” — that is, enrollments that may show some evidence that the applicant’s estimate of next-year income has been optimized to maximize subsidies. That segue is parroted by CMS in last week’s ASPE brief:

Enrollment that is improper or fraudulent is enrollment by individuals misstating their income to gain access to free plans. Phantom enrollees are unknowingly enrolled in free plans by brokers or auto enrolled. By our estimate, improper, phantom and fraudulent enrollment peaked at 5.6 million people in 2025.

2. The allegations of outright fraud — “phantom” enrollees signed up by brokers, who have no knowledge of their enrollment or no intent to use it— are chiefly based on an analysis of CMS data on ‘enrollees without claims’ (EWOC). This analysis, which ignores the high incidence of short-term enrollment in HealthCare.gov states, driven by year-round enrollment and by the Medicaid unwinding of 2023-2024 — has been effectively rebutted by Matt Fiedler (1, 2) and others. While broker fraud may have given some boost to EWOC, true “phantom” enrollments are small percentage of the enrollments branded as “improper.” As last week’s ASPE brief notes, “In 2025, CMS canceled coverage for 250,000 people enrolled without consent and identified 200,000 unauthorized plan switches.”

Thursday, June 11, 2026

Fleshing out the ACA marketplace's alleged phantom enrollees

Note: Free xpostfactoid subscription is available on Substack alone, though I will continue to cross-post on this site. If you're not subscribed, please visit xpostfactoid on Substack and sign up.

If you stop paying for your ACA plan, do you exist?

Now cometh Brian Blase and his colleagues from the right-wing Paragon Health Institute with his third iteration of the so-called “Great Obamacare Enrollment Fraud” (rechristened “The Persistent Obamacare Fraud”) — this time claiming 6.2 million “improper” enrollments .

I wanted to get “fraud” and “improper enrollment” in one sentence, because Blase conceptually segues from outright fraud— people enrolled without their consent, or under false pretenses — to “improper” enrollment, which he defines as enrollments in which the applicant’s future-looking income estimate may have been optimized to her advantage — usually by a broker. The original report deemed all enrollments with allegedly massaged income “fraud.”

Paragon’s core claim, which has not changed substantially since the first iteration of this report in 2024, is that the number of enrollees who estimate 2026 income in the 100-150% FPL range — 10.7 million, or 46% of all enrollees — far exceeds the Census Bureau’s survey-based estimates of the eligible population with income in that range. It’s doubtless true that many enrollees optimize their income estimates, usually at a broker’s direction - -e.g., to get over the 100% FPL eligibility thresholds in the 10 states that have not expanded Medicaid (available to adults with income up to 138% FPL in expansion states), or to get below 150% FPL, the eligibility threshold for the highest level of Cost Sharing Reduction (CSR).

Tuesday, December 16, 2025

Talking points for an electoral death march

Note: Free xpostfactoid subscription is available on Substack alone, though I will continue to cross-post on this site. If you're not subscribed, please visit xpostfactoid on Substack and sign up.

A man may smile, and smile (sort of)...

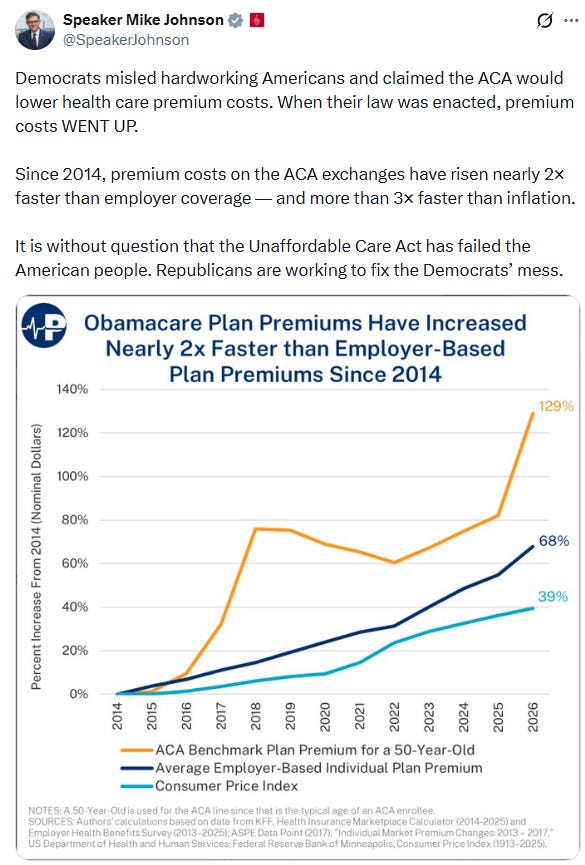
Multiple Republican senators and House reps, psyching themselves up for electoral suicide, are sharing this messaging from the Koch-funded Paragon Health Institute, where virtually all their ACA-related talking points originate:

There are of course lies, damned lies, statistics, and Koch-funded talking points designed to strip Americans of healthcare access to help fund tax cuts for the wealthy.

Look at the mid-section of Johnson chart above, from 2018 to 2025 (there should be a sharp spike from 2017 to 2018, but never mind). There is barely any premium increase in that long stretch, during which average premiums for employer-sponsored insurance rose far more quickly. Here is the comparison in the National Health Estimate Accounts, published in June of this year (see Table 17 in NHE Projections - Tables, here)


From 2018 through 2023, the last year for which the NHE has data, premiums in the individual market (“direct purchase” above) were up 13% — while premiums in the employer-sponsored market rose 29%. From 2023-2025, average ACA benchmark silver premiums rose 9% (from $456/month to $497/month), while average ESI premiums rose 11% (from $8,435/year to $9,325/year) for single coverage according to KFF’s annual employer benefits survey. As of 2025, ESI premiums remained considerably higher than marketplace premiums, though the difference is probably in line with differences in network quality and actuarial value (a measure of the level of out-of-pocket exposure).